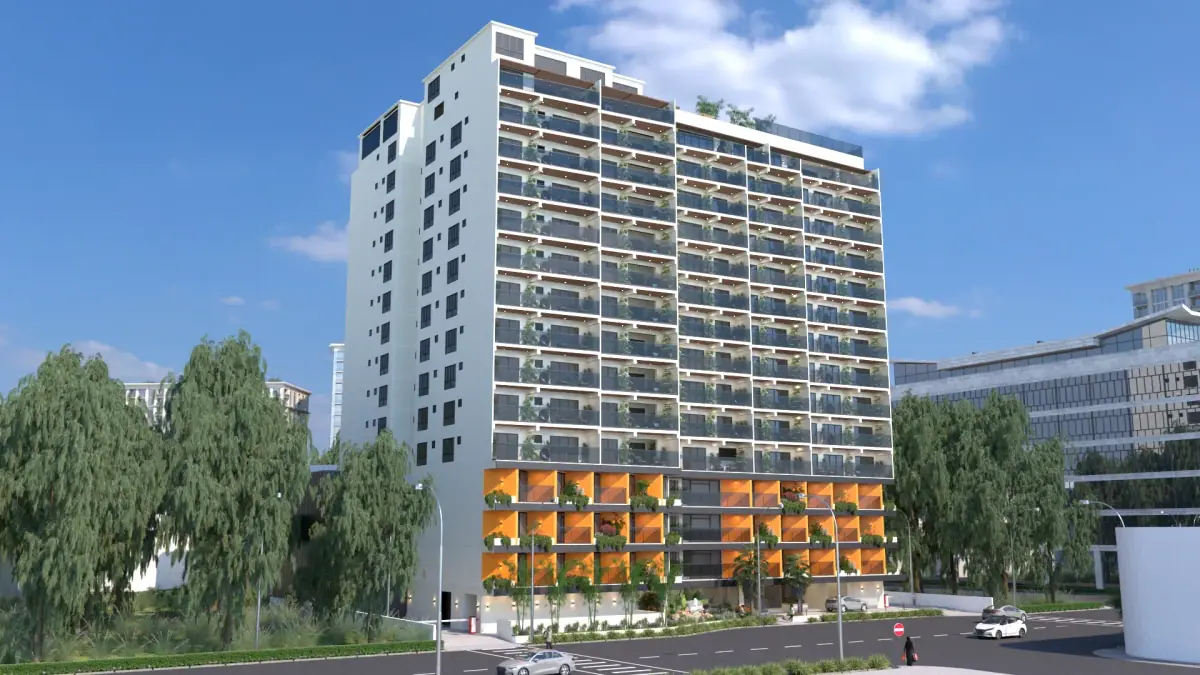
Set SJ Dhihereya's list prices against what three-bedroom homes in Hulhumalé Phase 1 are asking in rent today, and a gross yield of roughly 8 to 10 per cent appears on paper. Here is how that figure is built, and the five things that bring it down.
SJ Group's booking terms for SJ Dhihereya Residence in plain words: who is served first, what the 2 and 5 per cent discounts are worth, what a cancellation costs, and ten questions to settle before paying for a home due in 2028.
What daily life looks like from SJ Dhihereya Residence: west-facing homes over the lagoon, the ferry and the airport close by, and Hulhumalé Phase 1's parks, schools, shops and hospital within easy reach.
Yes, until you turn 60, but only half your balance, and the loan must be paid off before you turn 65. That shortens the term and raises the payment: on MVR 2.4 million at 11%, about MVR 33,100 a month over ten years against MVR 23,500 over 25.
The Pension Office does not pay out pension savings for housing. It lets members pledge them as collateral, in place of a cash down payment, and the money keeps earning. Why the scheme is built that way, and what it means for your retirement.
Only five institutions can take your pension savings as a home loan deposit: Bank of Maldives, Maldives Islamic Bank, HDFC, Mauritius Commercial Bank and Commercial Bank of Maldives. How the request moves between you, the lender and the Pension Office, step by step.
Under the Pension Office's housing scheme, a lender must sell the home first. Your pledged pension is used only if the sale does not clear the loan. The order of events, a worked example, and what to do before it comes to that.
The pension housing scheme is open to Maldivian MRPS members under 60. Self-employed people can join the MRPS voluntarily and build a balance; dollar earners contribute in rufiyaa; foreign residents can join the MRPS but cannot use it for a home. Who can, and how.
The Pension Office's housing scheme covers homes bought to live in, sold on the open market, including flats handed over when construction finishes. What that means for buyers in Greater Malé's new developments, and what it leaves out.
It depends on your age and your balance: all of it up to 35, 80% from 36 to 49, half from 50 to 60. Worked examples at each age, and how that compares with the 10% or 20% deposit lenders ask for on a MVR 3 million flat.
The Pension Office answers six questions about its housing scheme. Here they are with the answers, plus what each means for someone buying a flat from a developer, and two corrections where the FAQ's wording says the opposite of what the scheme does.
The Maldives Pension Administration Office's Dhivehi leaflet on using pension savings to buy a home sets out the whole scheme on four pages: who qualifies, how much you can pledge at each age, which homes count, the five lenders, the three steps and what happens to your money. Here it is in English, section by section.
Pledging pension keeps your cash free and may get you a lower rate; paying cash keeps your retirement savings out of the loan. Five questions to decide, and how to combine the two.
The Pension Office charges no fee for the housing pledge that we could find, and the money keeps earning. Some lenders even price pension-backed loans lower: HDFC charges 10.42% against 11%, about MVR 1,000 a month less on MVR 2.4 million. The real costs are risk and lost flexibility.
Pension savings pledged for a home are not frozen in place: they stay invested, or the lender pays returns on them, and come back to your account when the loan is repaid. How the returns work, what the MRPS invests in, and what it costs.
The 2026 amendment widens the MRPS for self-employed people. Because the pension housing scheme lets members pledge their savings instead of paying a cash deposit, a self-employed person who builds an RSA balance now builds a home deposit too. How to start, and how fast it adds up.
Since May 2026 the Pension Act lets members pledge pension savings for a loan to build a house. For a family with a plot, that could cover the equity a construction lender asks for. The construction loans available today, how pension could fit, and the questions to put to your lender while the regulations are written.
The 2026 Pension Act amendment lets members pledge pension savings for a loan to renovate an existing house. What renovation loans cost today, from HDFC's 11% Home Improvement to MFLC's Green Loan, where a pension pledge might help, and what to wait for.